The report contains data provided by Reuters, ICCO, HCCO, Hedgepoint
1.Season 2026/2027
Ivory Coast
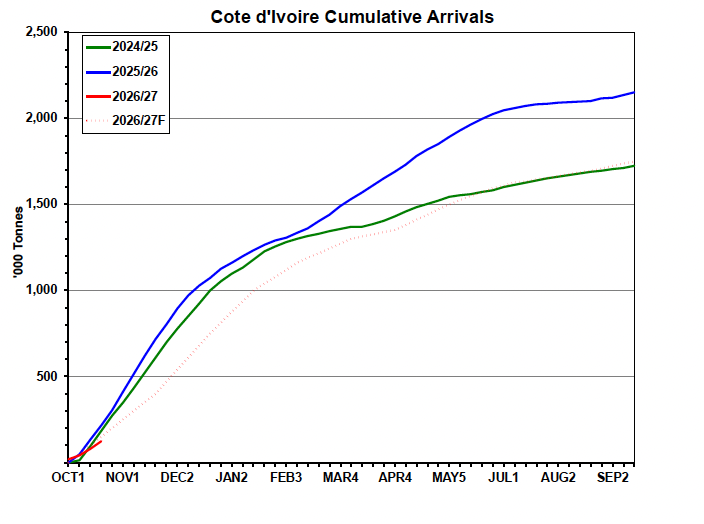
Port arrivals are expected to be below 2024 levels due to the significant impact of El Niño on the crop, as well as a stronger Harmattan (a dry northerly wind blowing from the Sahara) and its impact on crop yields.
Ghana
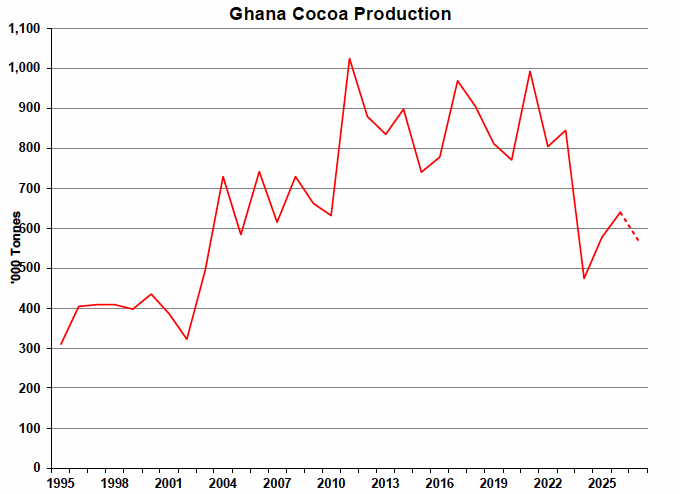
The crop has been declining since 2019, and there is still no clear indication of how Ghana will address its structural problems, provide support to farmers, and resolve its public finance issues.
Ecuador
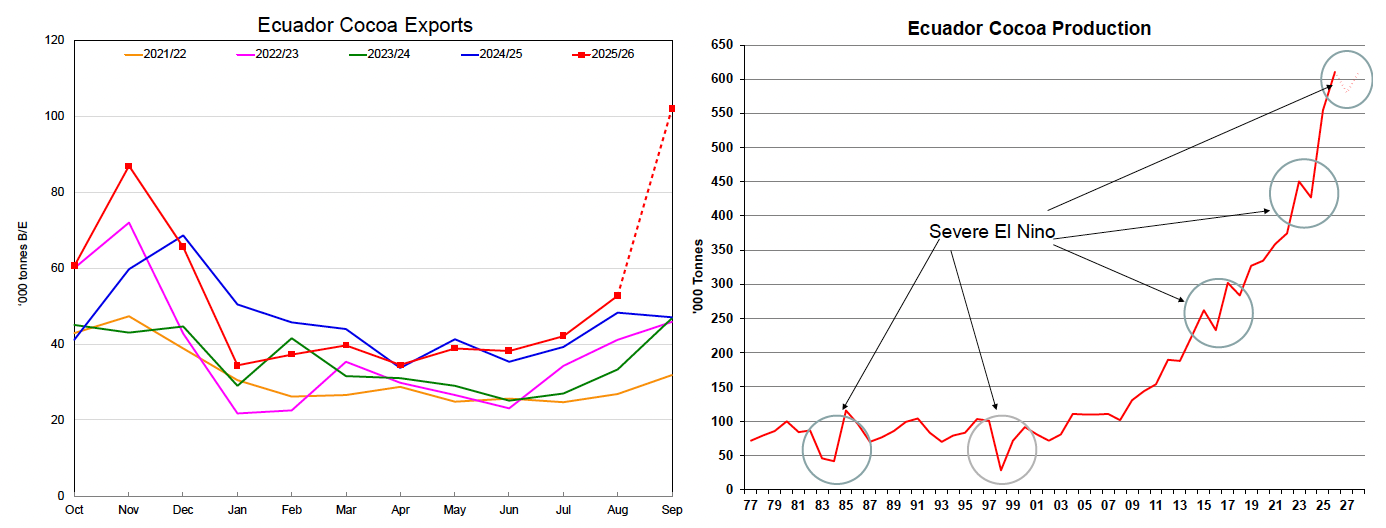
Exports from Ecuador are increasing. However, it is worth paying attention to the historical impact of strong El Niño events on crop yields. Given the heavy rainfall, we may see a slight decline in yields over the coming year.
Global cocoa grindings
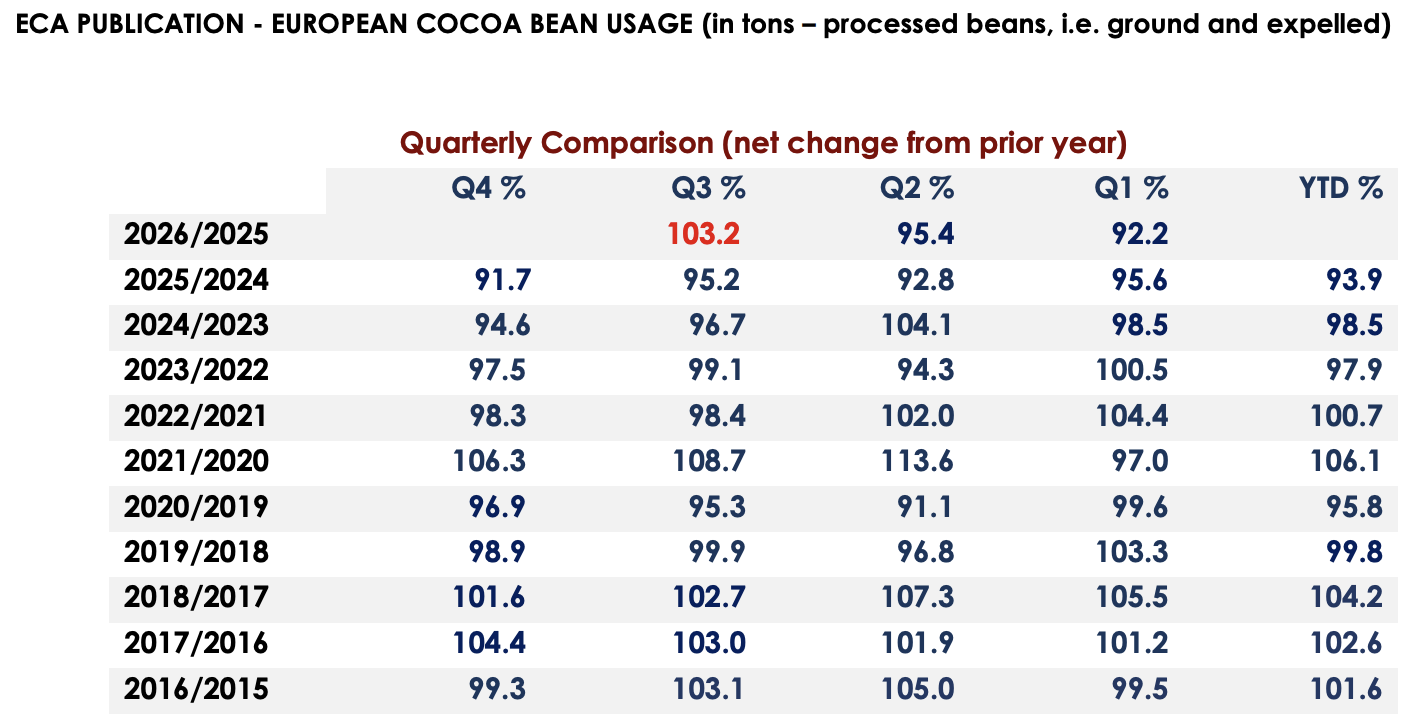
This is the second positive quarter in the last 3.5 years (14 quarters), with grindings increase by 3.2%.
However, these figures remain low, with grinding volumes still at 2020 levels, when the pandemic was underway.
US Grindings
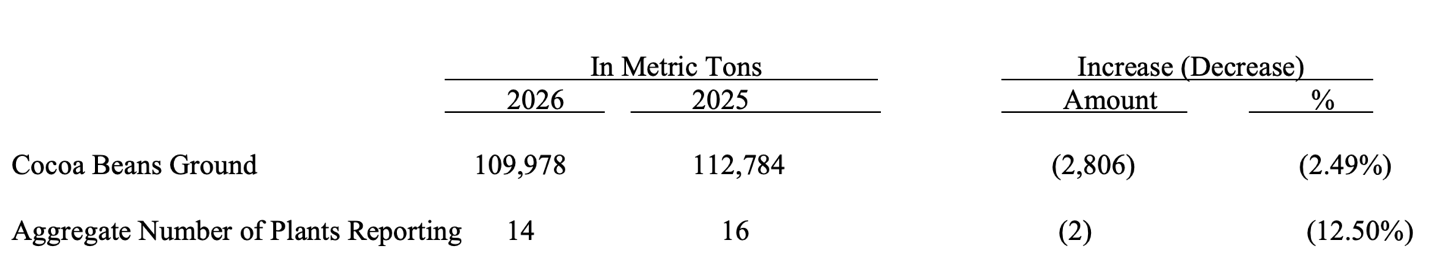
Grindings decreased by 2.5%, but two plants did not report their figures. In theory, this could suggest that grindings actually increased. Of course, it is possible that some plants have stopped processing cocoa beans and switched to processing cocoa products instead, but this remains just a speculation.
These figures confirm that consumption in this region also remains on an upward trend.
Asian region
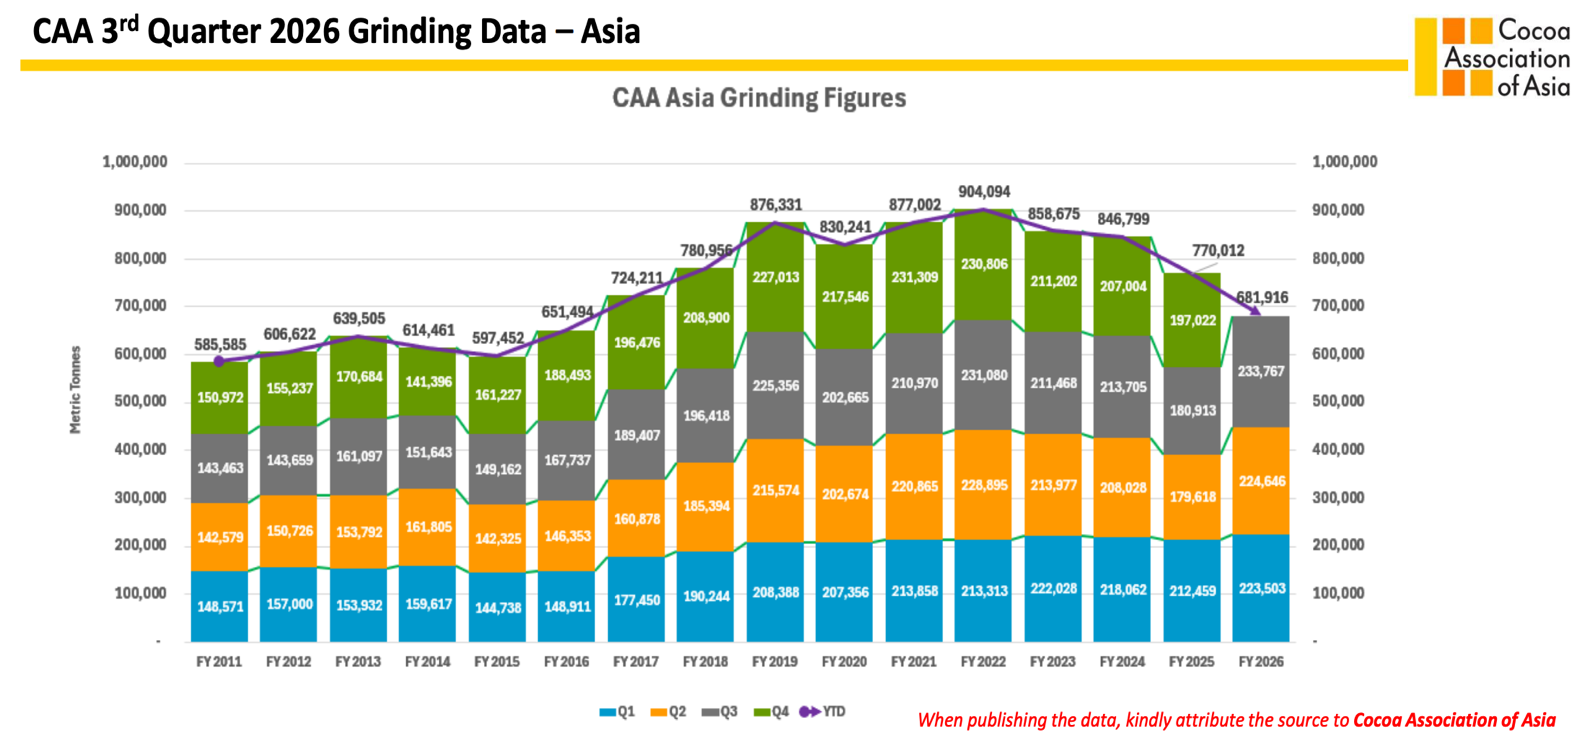
The boom in cocoa grinding is concentrated in Asia, where volumes increased by 29% year on year basis.
This quarter marks a record high for the entire period covered by available data.
If the trend continues, we will see the highest annual grinding volume ever recorded.
These figures are driving cocoa powder prices higher, as historically the Asian market has been a consumer of this particular cocoa product.
As of today, the exchange-traded price stands at EUR 5,100.00 per metric ton.
FOB West Africa ratios for spot deliveries are at the following levels:
Cocoa Liquor
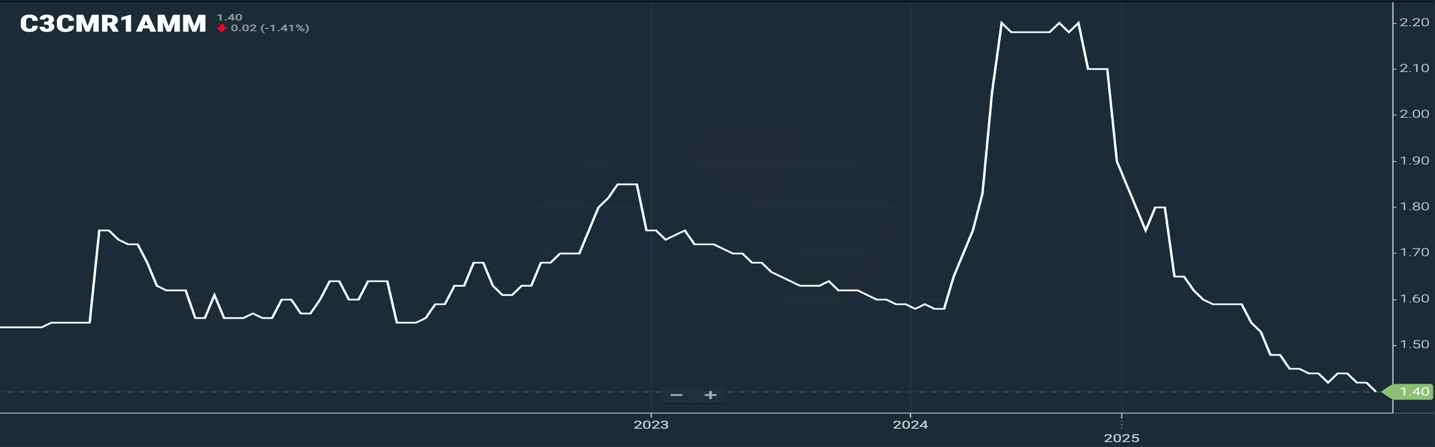
A ratio of 1.40 indicates temporary stabilization in this product, but only movements in the exchange-traded price will reveal the direction of the future trend. At present, the differential on cocoa beans is playing the most significant role.
Natural Cocoa Butter
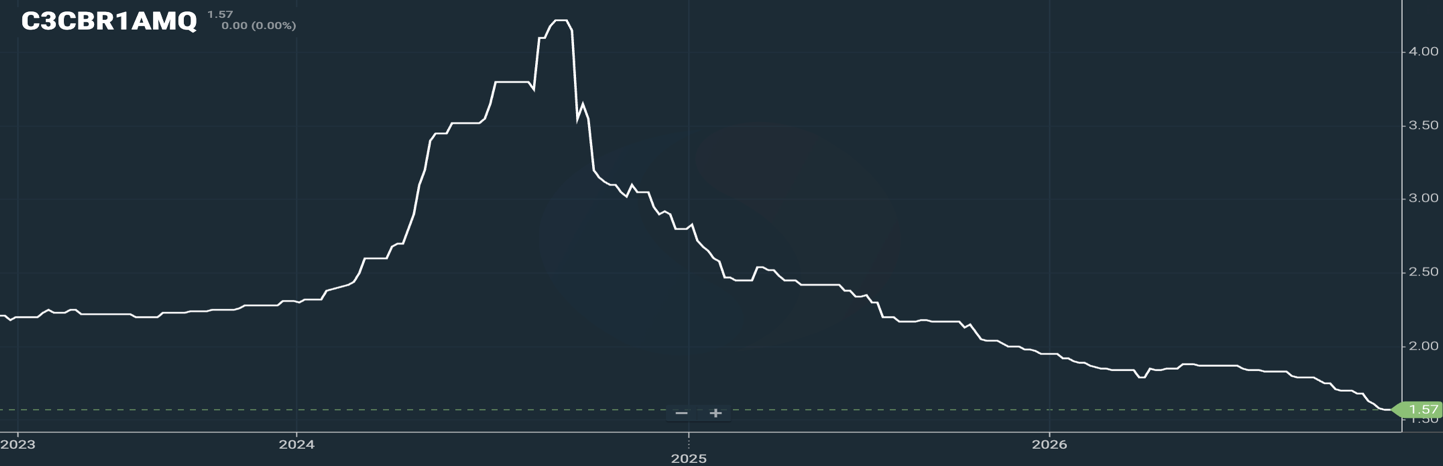
The ratio for natural cocoa butter stands at 1.57 and indicates a downward trend, driven by high cocoa powder prices.
Cocoa Powder
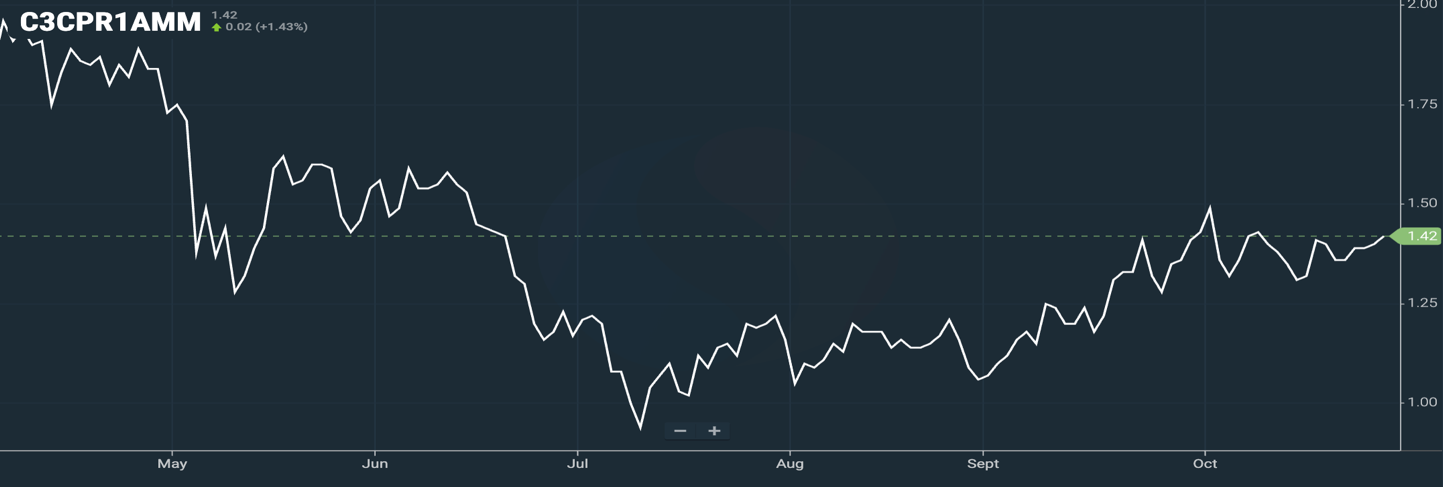
The cocoa powder ratio continued to rise from the previous month. It currently stands at 1.42 relative to the exchange price and has already surpassed the ratio for cocoa liquor
2.Technical Analysis
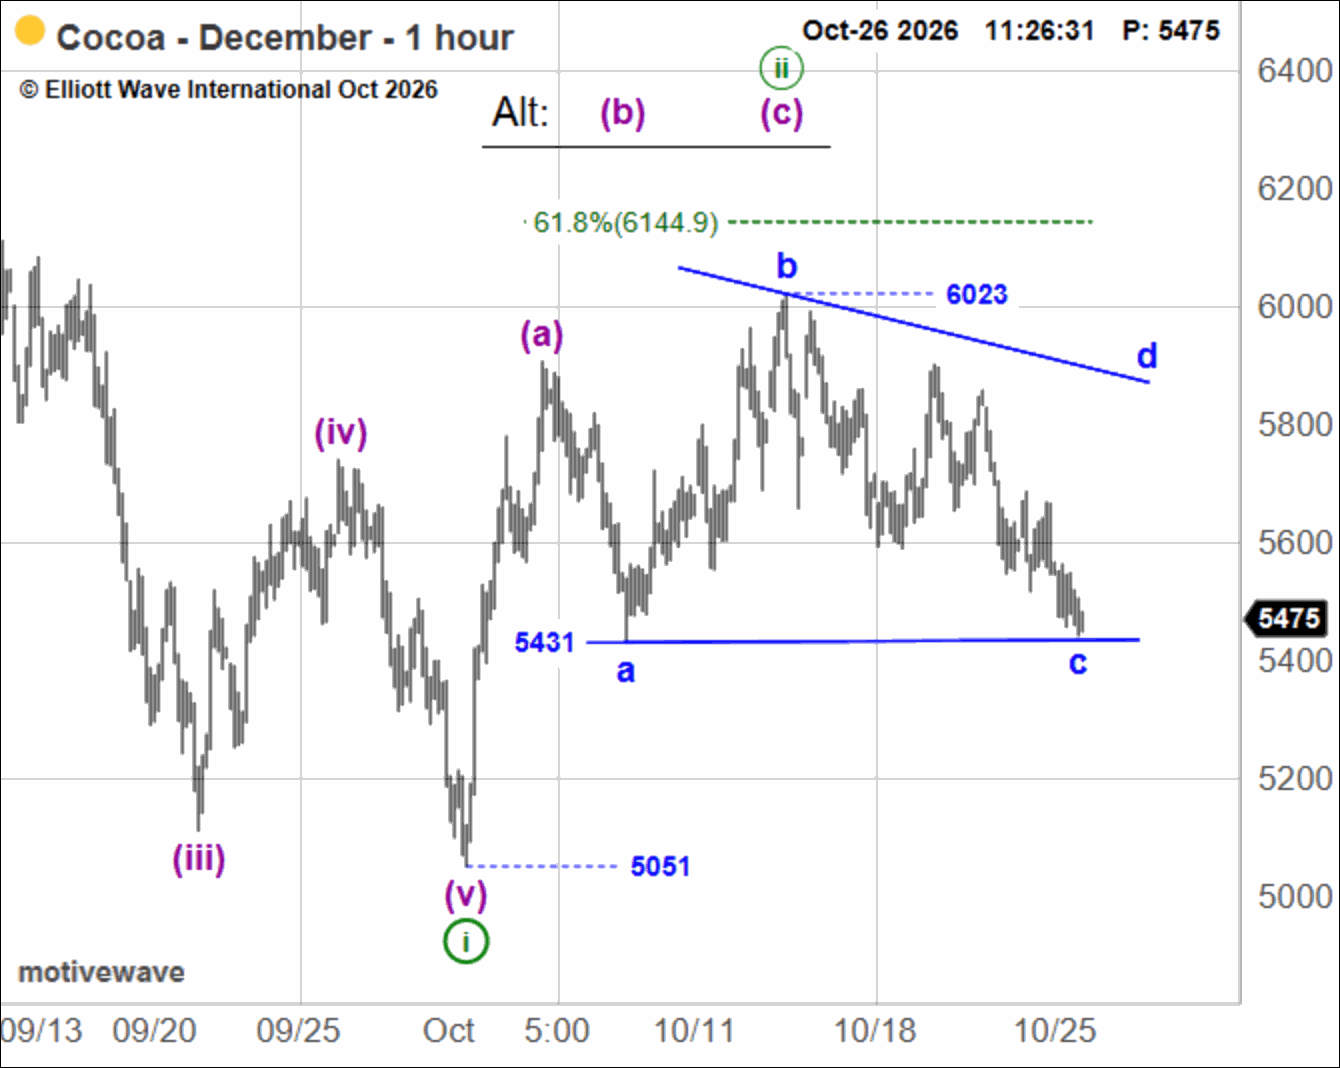
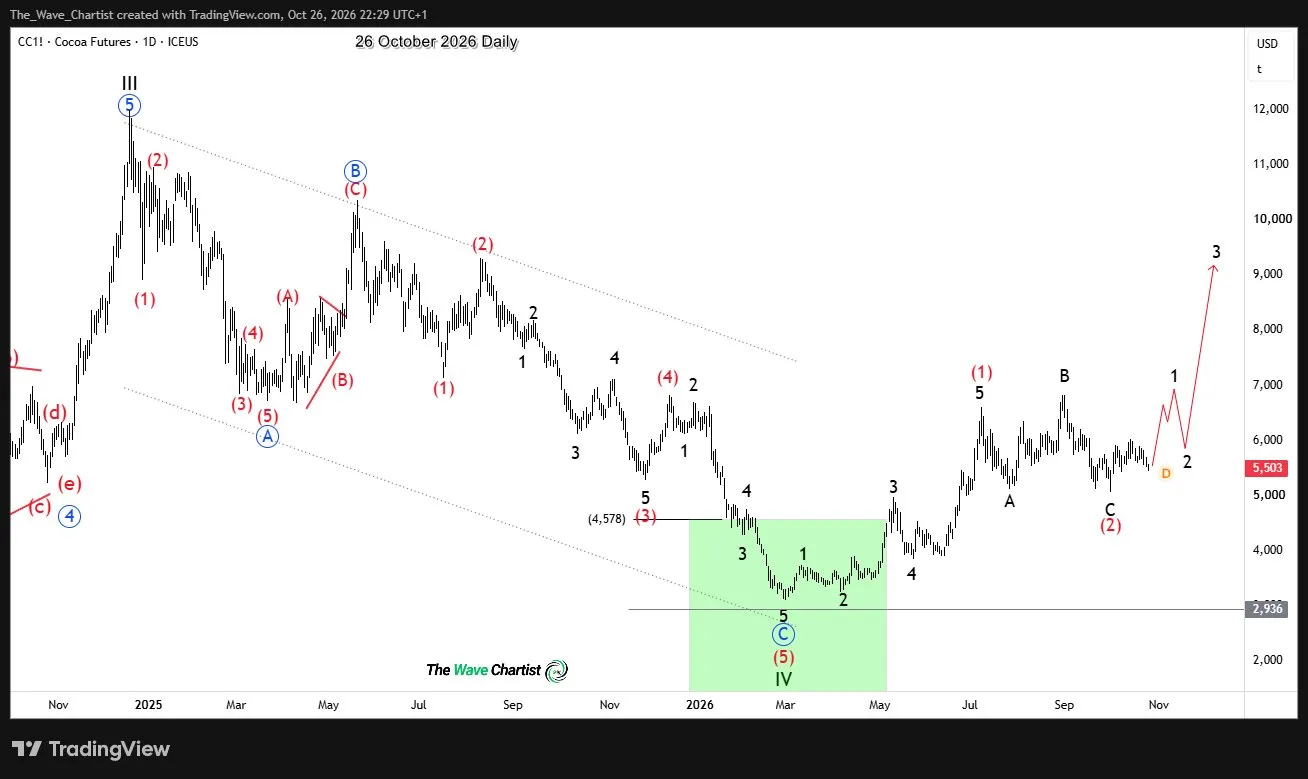
The market is still at a crossroads. Two completely different scenarios can be considered for cocoa. The situation has changed very little throughout October.
Bearish scenario
A break below 5,051.00 could trigger a further decline toward 3,000.00 and below on the New York market. Factors supporting this scenario include low trading volumes in recent weeks and technical pressure from hedge funds.
Bullish scenario
Factors supporting this scenario include the impact of El Niño, strong cocoa grinding data, and weak arrivals at ports.
Could the market start rising now, when everyone is expecting further declines?
Both scenarios have a strong chance of materializing. It is entirely possible that we will see one or the other unfold within the next few days or weeks.
We need a catalyst. If the momentum is downward, the first scenario is the most likely to play out. However, if we see a sharp upward surge, we would expect the second scenario to materialize.
WEATHER
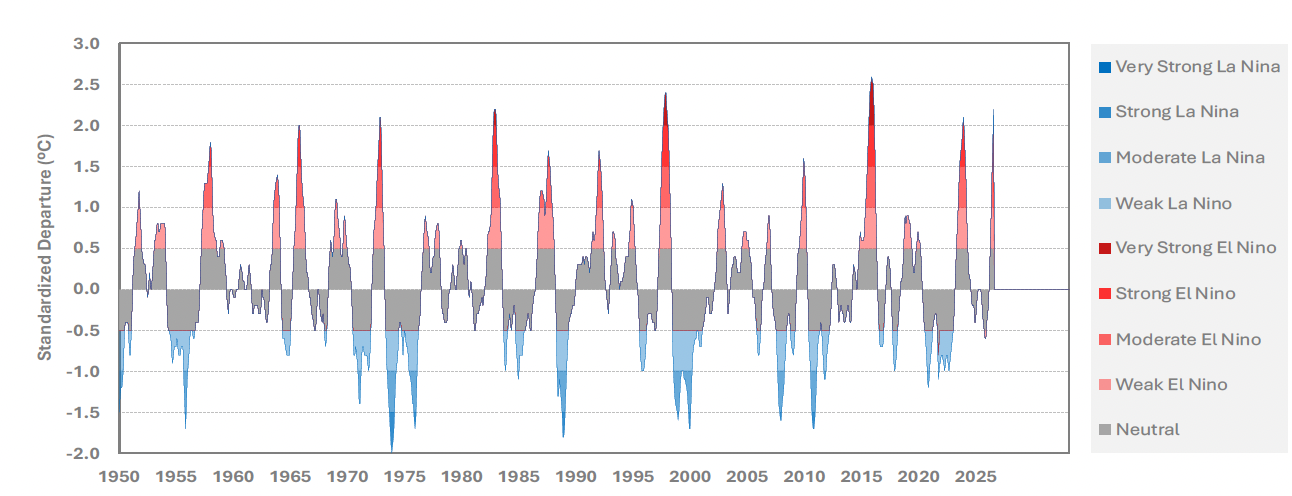
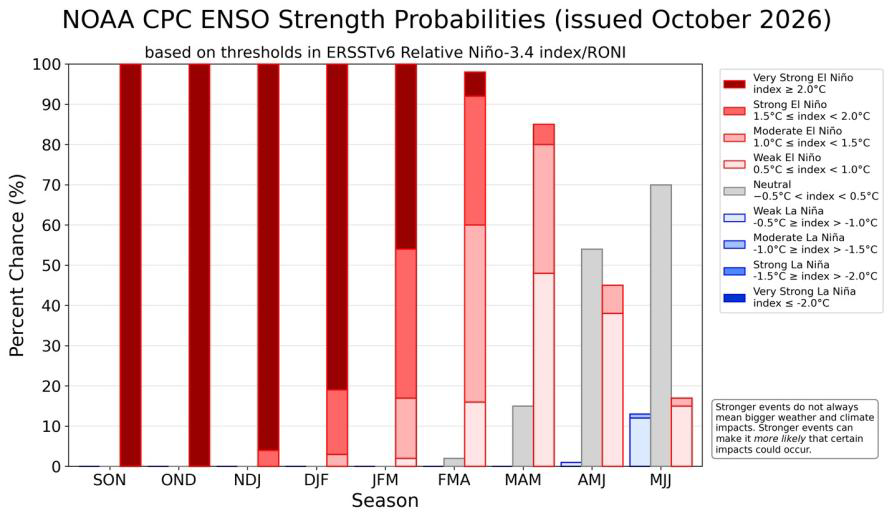
El Niño is intensifying and, by all indications, is expected to be one of the strongest events of the past 10 years. According to forecasts it is expected to maintain its strength at least through March 2027.
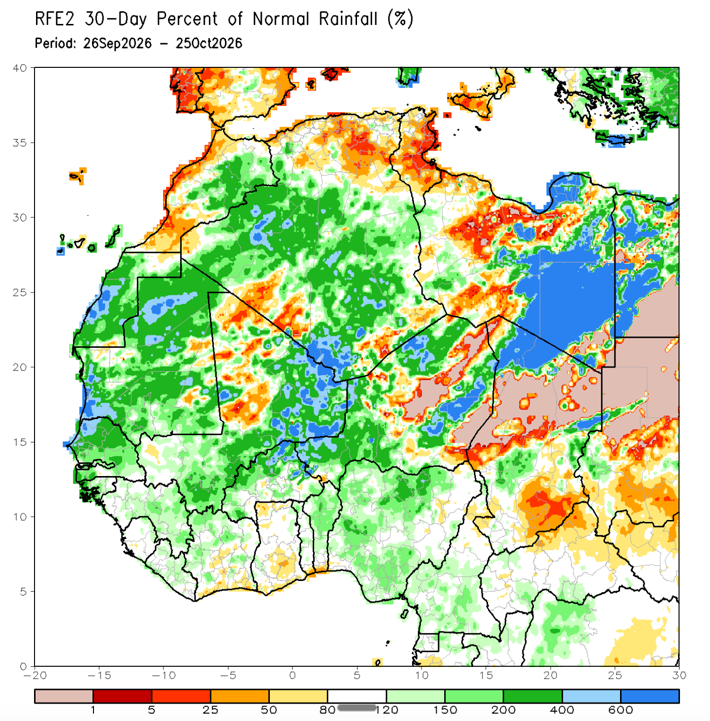
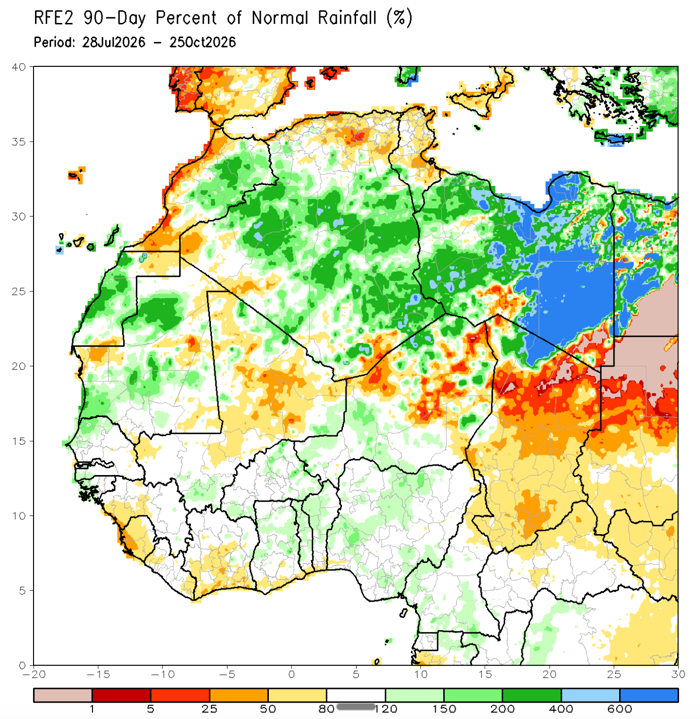
Rainfall levels have remained below average over the past 90 days. However, over the last 30 days, rainfall across Africa has been relatively favorable, which is somewhat unexpected given the extreme El Niño development forecasts.